European online casino markets are some of the most developed in the world. The UK is a prime example. In 2025, online casino revenues reached approximately $6.5 billion. Furthermore, online casino customer registrations were broadly flat, which signifies that operators are able to generate more revenue from their current customer base as opposed to building a new customer base. Elsewhere in Europe, Italy, Sweden, and Romania have their own established regulatory structures and have limitations on the overall size of their markets. The US market is also developed, but in a different way. In 2025, iGaming revenues from states with an established iGaming market reached approximately $10.73 billion. The main reason for this interest is that the European market is established, competitive, and large, but mature and slower-growing, while North America is at an earlier stage of growth. This provides the main impetus for European iGaming operators to expand into new markets.
Romania shows important traits when it comes to regulated European markets. Since 2015, the local industry has developed a strong channelization model that ensures the vast majority of customers play on regulated platforms. With channelization levels above 90%, the majority of the local market is accessible to licensed operators. This is a key factor when assessing a market’s revenue potential. The consistency of Romania’s channelization model has attracted more established operators, as they are able to more easily assess and manage business risks. By 2025, over 30 online operators were active in Romania.
For those that focus on the iGaming industry, Romania is a prime example of how a mid-market iGaming opportunity can flourish. Romania has a developed iGaming market that draws players. Don Casino is an excellent example, as it provides players a multitude of iGaming opportunities including online slots and live table games.
Romania also shows why channelization matters: it determines how much of a market’s theoretical size is actually accessible to licensed operators. A market’s headline size matters only if operators can reach the players inside it.
Where the money already is
Europe’s online gambling industry is thriving. Online GGR in Europe was estimated at €47.9 billion, an 11.7% increase year-over-year. The European online gambling industry is dominated by online casino games. Online casino games generated €23.2 billion or 48.3% of the total online GGR in Europe. Let’s take a look at the top performing markets and the trends driving growth.
The UK is home to the largest online gambling market in Europe. The UK’s online casino industry generated an estimated GGR of £5 billion. Like many other developed markets, the UK online gambling industry is considered to be mature. To continue growing, UK operators must optimize their offerings to deepen player engagement.
Italy’s online gambling market is estimated at roughly half the size of the UK online gambling market. Like the UK, the Italian online gambling industry is considered to be mature and is highly regulated. In fact, most European online gambling markets are regulated, and the industry limits restrain the growth of most operators active in Europe.
The above analysis shows that Europe’s online gambling industry is mature. Considering the strict regulations, highly developed markets, and saturation of the industry, further growth in Europe is difficult, making expansion outside Europe more attractive.
The cost of playing the customer acquisition game
Just like an auction with many bidders, customer acquisition in the UK and Swedish iGaming markets follows the principle of offering the highest price to win the auction. Operators set prices based on what they think an online casino customer is worth. Very few adults in the UK and Sweden who are interested in online casino have not played on a regulated site. So the available customer base is small. Compared to a few years ago, the cost of customer acquisition has increased and the period to recoup the cost has also increased.
The situation in Sweden is slightly different. The way the Swedish government has structured licenses and their terms shapes the incentives available to operators and their customer acquisition strategies. The online casino channelization in Sweden was estimated at 57%, which is lower than that of Romania. The channelization of a market helps regulated operators monetize the market potential.
The case for customer acquisition in a mature regulated market becomes increasingly unattractive. Ultimately, the case for customer acquisition in a less saturated, receptive market becomes more attractive. It is through this line of thinking that an iGaming company justifies international market expansion.
Geography as a key driver for growth
A solution to the problem of stagnating growth is to expand to previously unreachable markets. For iGaming this creates an interesting opportunity, since markets like the US or Canada present a sufficiently different environment from EU markets, resulting in different consumer behavior and therefore more attractive return potential.
Let’s look at revenues first. An iGaming operator working predominantly in European markets is exposed to a range of risks including unpredictable changes in local regulations and taxes and fluctuations in consumer behavior. The introduction of a new product or service in a different market can reduce this concentration. As mentioned previously, the player base in Europe is more mature and therefore less mobile. North American markets operate on a different regulatory cycle, so the two revenue streams do not necessarily move together.
Let’s look at costs next. Launching a casino in a new market represents a significant cost, particularly in regulated markets. However, for an operator already active in other markets, the incremental cost to enter a new market can be substantially lower than the average cost incurred in the initial market.
Growth across North America
In 2024, the U.S. iGaming market reached an estimated $8.41 billion, with a 28.7% growth from the previous year. At that point, there were seven states with operational online casino markets. Rhode Island joined the U.S. online casino market in March 2024, the first new US iGaming state since Connecticut launched in late 2021. The markets operate at an early stage of the product lifecycle and have the potential to attract a large, prospective consumer base.
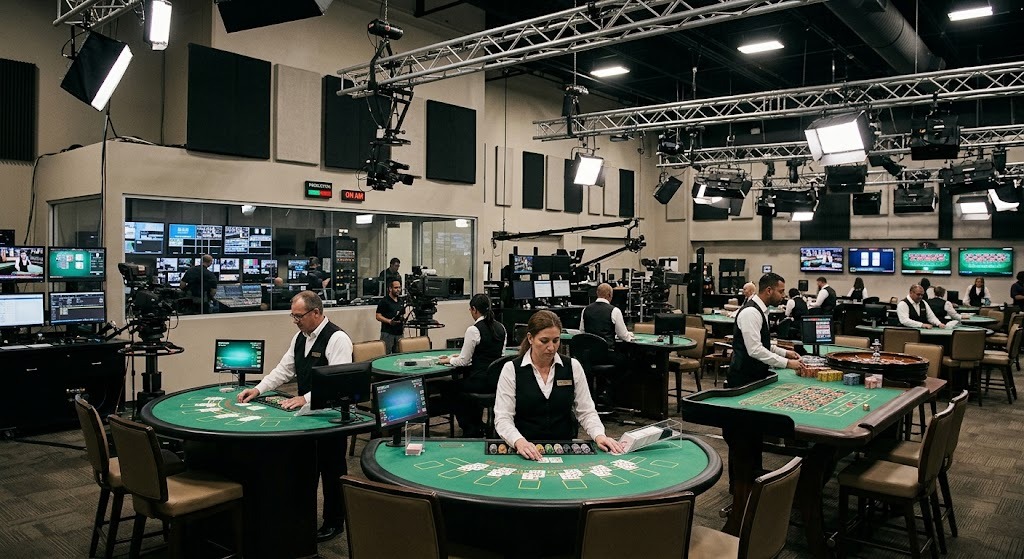
As of 2024, the states of Michigan, New Jersey, and Pennsylvania were the largest markets, with each state generating over $2.8 billion. These markets have a mature, developed state of play, with gaming companies like Evolution Gaming and Playtech establishing local studios and operations.
Although smaller in scale, the Canadian market provides comparable information. In April 2022, Ontario legalized and launched its online gaming market. For the 2024-2025 fiscal year, the province reported gross gaming revenue of 3.20 billion Canadian dollars, a 32% increase from the prior year. Compared to U.S. markets, which are still maturing, and European markets, which are more established, Ontario’s market represents what is possible with compounding growth and product improvement.
Insights from companies with operations in North America show that revenues from North America are growing much faster than revenues from Europe, while European revenues are still higher.
What do the transatlantic numbers mean?
From a capital allocation perspective, the numbers tell us that a higher-growth, albeit smaller, market can compound faster than a larger, more established market. This is especially true when the company already has the necessary assets to compete in the market.
There are other considerations as well. From the perspective of the customer, the company entering a new market has the opportunity to acquire customers with a long runway in front of them, unlike customers in more established markets. This is especially true when the new, less developed market is growing and has strong channelization. An operator that has developed strong customer relationships in Europe has the potential to establish similar relationships in North America.
Challenges of market presence in North America
There are several similarities in the business and growth strategies of Europe and North America. However, on a more operational level, some important modifications would have to be made to the European online casino business before it could be established in North America.
There are variations in game preferences that impact game and product offerings. Popularity of live dealer games has increased in certain US states as the dealer and table game setup is easy to understand. However, the game variants that are popular in New Jersey may differ because local player preferences differ and take time for providers to analyze and understand. The preferences of game players may also explain the variations seen in the popularity of slot games in different jurisdictions. Slots that are popular in European online casinos may not be popular in online casinos in US markets.
Of all the factors affecting the iGaming industry, the payment processing system remains one of the most challenging. Payment methods used by game players in Europe may differ from payment methods used by game players in North America. Additionally, the licensed payment service providers used in US gaming states may be less developed compared to payment service providers used in the UK and Sweden.
From a regulatory and compliance perspective, each state has its own requirements for ID verification, self-exclusion, and marketing, and these increase the cost of doing business. Whether the additional costs to do business in a new state are recouped is the question management must consider. In the current state of the US iGaming market, the revenue opportunity can justify those costs for operators with the right platform scale.
Platform Architecture Drives Geographic Expansion
Geographic growth makes more financial sense for established operators because of the nature of platform architecture. An online casino platform is composed of multiple, often independent, layers. For example, there are layers for game aggregation and integration, player account and session management, and payment and compliance. The economics of entering a new market are greatly impacted by how easily the layers of the platform can be adjusted to accommodate the rules and regulations of that market.
Established operators build their technology platforms to operate in multiple jurisdictions and can often adjust their technology to enter new markets. Once a technology platform is developed for the first market, the additional margin earned from a new market can be significant. Platforms for online casino and gaming operations have powerful economies of scale because the costs to develop and build the technology are mostly fixed, and the costs to serve additional markets are much lower.
Live dealer studios are the exception to the rule when talking about how quickly gaming companies can expand their operations in new states. Evolution Gaming built studios in Michigan and New Jersey, and those studios cannot easily be moved to new states the way software can. Since the studios are fixed in those states, expanding live dealer games into a new state requires additional physical investment. As such, it appears live dealer games typically follow the path of RNG games, at least in the United States.
Where the Economics Get Complex
The dynamics of the US market are different from other markets. New York is a good example. New York’s decision to tax sports betting GGR at 51% created a market with tight operator margins. It was a good example of where an operator had to be cost conscious to succeed. New York was a good example of why operators have to be conscious of the state’s tax policy when looking to enter a new market.
Plans have to be stretched out to account for lengthy licensing and rule-making processes. It can take two to four years after a state signals its intent to regulate sports betting before operators are allowed to take wagers. Capital committed to a state may be tied up for a longer period, and by the time a state allows sports betting, it may be in a more competitive environment.
While the size of the market may be large, the amount of revenue generated may be small. The adult populations in large states may represent large addressable markets, but the number of people who play online casino games and do so through a licensed operator may be very small. In new markets, that share may be hard to predict. Based on figures from Ontario’s regulated iGaming market, a well-run market can reach real scale within three years. The Ontario market may be a good case study for new markets in the US, but it may take longer to generate the revenue expected from the total market potential.
The expansion calculation
This calculation considers the main challenges operators face when expanding into new jurisdictions. These include the variability of tax rates, the cost of compliance, and the speed at which a licensee can roll out its offerings. There is also the significant up-front capital cost of live-dealer offerings. The best positioned operators to enter a given market are likely those with the most scale. That’s because those operators will typically have the most flexible capacity and the lowest average cost to serve a given market.
When it comes right down to it, operators are betting on the similarity between the current state of the iGaming industry in North America, and about 10 years back in Europe. They see the positive trajectory of the European iGaming industry, and are no doubt encouraged by the early evidence coming out of Ontario and the established US markets.